
Wind damage claims in McAllen are driven mostly by severe thunderstorms rather than tornadoes. NOAA Storm Events data for Hidalgo County lists more than 200 thunderstorm wind reports, with most in April, May, and June. Two recent events show what local wind can do:
- April 28, 2023: NWS storm surveys estimated gusts near 85 mph in McAllen. Surveyors found more than half the shingles off a two-story building on S 29th Street, roof and wall failures along W Business 83, and aircraft flipped at McAllen-Miller International Airport (NCEI event record). Damage was also reported in Mission, Pharr, San Juan, Edinburg, and Weslaco.
- May 8, 2025: A strong microburst from a hail-producing supercell struck north McAllen near the Edinburg city line, with estimated gusts near 85 mph and damage mainly to more than 100 large mesquite and live oak trees (NCEI event record).
When winds like these hit, insurance claim help in McAllen is in high demand. This page covers what wind claims involve and where they tend to get stuck. More local events are on our storm history page.
Types of Wind Damage Covered
Windstorm is a covered peril on most homeowners and commercial property policies, subject to deductibles and exclusions. Common wind losses include:
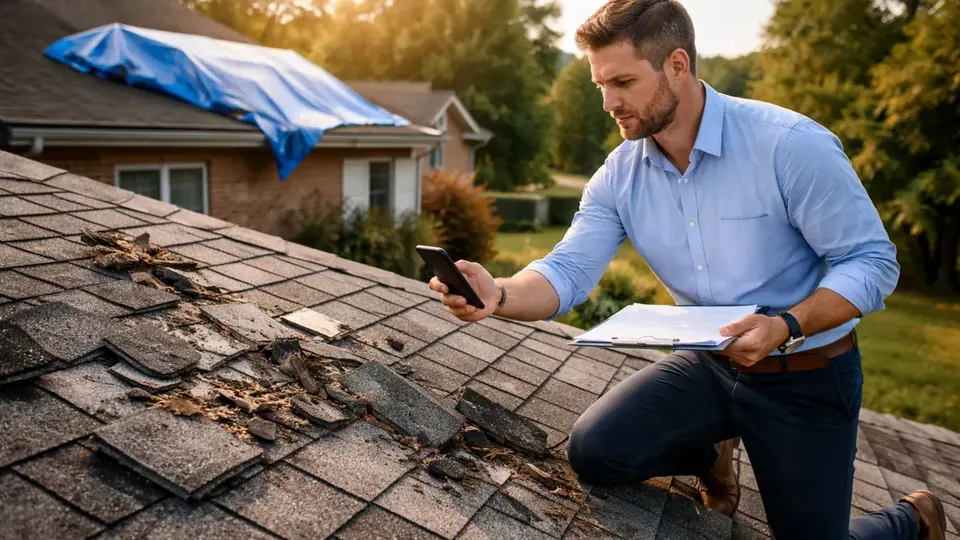
- Missing, creased, or lifted shingles; displaced tile; peeled metal roofing and flashing (see roof damage claims).
- Fallen trees and large limbs striking roofs, walls, fences, vehicles, and carports.
- Damaged fences, pergolas, awnings, and signage.
- Broken windows and doors, including garage doors blown in.
- Wind-driven debris impacts on siding and stucco.
- Rain entering through wind-created openings, causing interior water damage.
- Structural damage to metal buildings, mobile homes, and weakly connected roof framing.
Typical Documentation for a Wind Claim
| Item | What to capture |
|---|---|
| Photos and video | Every elevation, roof slopes, fallen trees in place before removal, debris, and interior stains. |
| Weather evidence | NWS storm survey findings, NOAA Storm Events entries, local wind reports for the date. |
| Tree service invoices | Removal from the structure, debris hauling, and cost breakdown. |
| Emergency repair receipts | Tarping, board-up, and water extraction. |
| Itemized estimate | Roofing, framing, exterior finishes, fencing, and interior repairs. |
| Contents list | Damaged personal property with age and replacement cost. |
Our claim documentation checklist lists more items.
Common Claim Issues and Insurer Arguments
- Pre-existing condition. The carrier says shingles were already brittle or poorly fastened, or that a tree was dead or decayed.
- Insufficient wind speed. The insurer relies on a distant airport reading. Microbursts are small and intense, so nearby surveys and local reports matter.
- Interior water excluded. The adjuster claims there was no wind-created opening, so the rain damage is not covered.
- Repair scope too narrow. Only visibly missing shingles are replaced, ignoring broken seal strips and creased tabs.
- Debris removal limits. Tree removal is capped or partially denied.
Insurance Settlement Considerations
- Wind/hail deductible. Often a percentage of Coverage A. A 1% or 2% deductible on a higher-value home can be significant.
- ACV vs. RCV. Replacement cost policies typically pay actual cash value first, with recoverable depreciation paid after repairs. See RCV vs. ACV in Texas.
- Ordinance or law. Rebuilding wind-damaged framing or roofing in McAllen must meet the 2024 ICC codes adopted effective January 1, 2026. Upgrade costs are paid only if ordinance or law coverage applies, up to its limit. See McAllen building codes.
- Separate limits. Fences and detached structures fall under other structures coverage; tree removal often has a per-tree and per-loss cap.
Fallen Trees and Debris Removal
Mature mesquite, live oak, and palm trees are common in McAllen neighborhoods, and the May 2025 microburst showed how many can come down in a single event. Tree claims usually turn on what the tree hit:
- Tree strikes the house or a covered structure. Damage to the building is typically covered under the wind peril, and removal of the tree from the structure is usually part of the claim.
- Tree blocks a driveway or accessibility ramp. Some homeowners policies provide limited coverage to remove it.
- Tree falls in the yard without damaging anything. Removal is often not covered.
- Tree from a neighbor’s yard. Generally your own policy responds to damage on your property, regardless of whose tree it was, unless negligence is involved.
Many policies cap tree debris removal per tree and per loss, so take photos of each tree in place and keep separate invoices for removal from the structure versus general yard cleanup.
How a Public Adjuster May Help
A licensed public adjuster can inspect the property, match the damage pattern to the storm, pull weather records, prepare a detailed estimate, and present the claim to the insurer. If the insurer has denied the wind portion or paid too little, see our denied claims and underpaid claims pages. We cannot guarantee any outcome. Fees are disclosed in a written contract before any work begins; Texas law caps public adjuster compensation at 10% of the insurance settlement.
Policyholder Responsibilities
- Report the loss promptly and note the date and time the wind hit.
- Photograph fallen trees before removal when it is safe to do so.
- Take reasonable steps to prevent further damage, such as tarping and board-up.
- Submit a proof of loss if the insurer requests one, within the stated deadline.
- Cooperate with inspections and document requests.
Applicable Policy Limitations and Exclusions
Wind claims may be limited by exclusions for wear and tear, deterioration, and faulty construction; limits on tree and debris removal; exclusions for interior rain damage without a storm-created opening; cosmetic damage endorsements; and flood exclusions when storm water rises from the ground. Policies may also impose deadlines to file suit. For legal questions, consult a Texas attorney.
Frequently Asked Questions
Is a microburst covered the same as a tornado?
Generally, yes. Most property policies cover windstorm damage regardless of whether the wind came from a tornado, a microburst, or straight-line thunderstorm winds. Deductibles and exclusions still apply.
Does insurance pay to remove a tree that fell in my yard?
Many homeowners policies pay a limited amount for tree debris removal when a tree damages a covered structure or blocks a driveway or ramp. A tree that falls without damaging anything is often not covered. Check your policy’s debris removal provisions.
The insurer says my missing shingles were already loose. What can I do?
Storm reports, photos of the roof before the storm, the pattern of damage, and damage to neighboring properties can help show the wind event caused the loss. A public adjuster can help gather and present that evidence.
Is my wind deductible a percentage?
Many Texas policies use a wind/hail deductible equal to a percentage of the dwelling limit. Your declarations page lists the exact amount.
Is McAllen in the TWIA coverage area?
No. Hidalgo County is not in the TWIA designated catastrophe area, so McAllen properties typically get wind coverage through their regular insurer or the Texas FAIR Plan where applicable.
Does wind coverage include rain that came in through the damaged roof?
Many policies cover interior rain damage only when wind or hail first creates an opening in the roof or walls. Documenting the opening is important.