Key takeaways
- McAllen sees damaging straight-line winds and microbursts, not just hurricanes. NWS storm surveys estimated gusts near 85 mph in McAllen on April 28, 2023 and May 8, 2025.
- Most wind claim disputes come down to one question: was the damage caused by a specific wind event, or by age and wear? Your documentation should answer it.
- Photograph lifted, creased, and missing shingles, damaged fences, and fallen trees before cleanup, and save the date and time of the storm.
- Many Texas policies have a separate wind/hail deductible, often a percentage of your dwelling limit. Check your declarations page before you assume the claim is not worth filing.
- If the estimate seems low or the claim is denied as "wear and tear," you can ask for a re-inspection, submit a supplement, or, for disputes over amount, consider appraisal.
When most people picture wind damage on the Texas border, they think of hurricanes. In practice, a lot of the wind damage that leads to wind damage insurance claims in McAllen comes from severe thunderstorms: straight-line winds and microbursts that drop out of a storm with little warning, peel shingles, flatten fences, and drop mesquite and live oak limbs onto roofs. This guide explains how wind claims work for McAllen and Hidalgo County property owners, how insurers tend to evaluate them, and how to document your loss so the facts are clear.
Wind is a real, recurring risk in McAllen
The NOAA National Centers for Environmental Information (NCEI) Storm Events Database lists more than 200 thunderstorm wind reports for Hidalgo County. They cluster in spring and early summer: May and April lead, followed by June and August. Two recent events show what these storms can do in the city itself.
April 28, 2023: NWS storm surveys in McAllen
Overnight on April 28–29, 2023, a severe wind event swept across Hidalgo County. National Weather Service storm surveys estimated gusts of about 74 knots (roughly 85 mph) in McAllen. On S 29th Street, surveyors found more than half the shingles stripped from a two-story building with full exposure to the west-northwest. At McAllen-Miller International Airport, a small plane was flipped onto its roof. Along W Business 83, part of a roof collapsed on a building with a tall cinderblock wall. Damage was also reported in Mission, Pharr, San Juan, Edinburg, Weslaco, Donna, and Progreso.
May 8, 2025: microburst in north McAllen
Just after 7 p.m. on May 8, 2025, a strong microburst descended from a hail-producing supercell in north McAllen near the Edinburg city line. NCEI lists an estimated gust of about 74 knots (roughly 85 mph), and damage was mainly to more than 100 large mesquite and live oak trees. The same storm produced hail up to 3 inches reported in the Shayland area. Storms like this often cause wind and hail damage together, which matters later when the adjuster starts sorting out causes.
You can look up storms near your address on our storm lookup tool or browse the McAllen storm history page.
What wind damage typically looks like on McAllen properties
Local construction shapes what fails in a windstorm. Most homes here are slab-on-grade with composition shingle roofs and stucco or brick veneer walls. Metal roofs are common on outbuildings and commercial buildings, and many businesses have flat or low-slope roofs. Typical wind damage includes:
- Shingles: missing tabs, shingles lifted and creased at the nail line, broken seal strips, and displaced ridge caps. Shingles at edges, rakes, and ridges usually fail first.
- Metal roofing and siding: panels peeled back at the eaves, popped fasteners, bent trim, and torn flashing.
- Fences: wood privacy fences leaning or flattened, broken posts, and missing pickets.
- Trees and debris: limbs on roofs, punctured decking, crushed gutters, and impact damage to vehicles and outbuildings.
- Openings: garage doors blown in, broken windows, and torn screens.
- Interior: water stains and wet insulation where wind opened the roof and rain followed.
Wind damage vs. wear and tear: where claims get disputed
Most policies cover sudden physical damage from windstorm and exclude wear and tear, deterioration, and defects. That puts the cause of the damage at the center of almost every wind claim. An adjuster who sees an older roof may conclude the missing shingles were already loose. A homeowner who watched the storm hit knows the roof was fine the day before. The evidence usually decides who is right.
Here is how the two often look on inspection:
| Evidence | Tends to suggest wind damage | Tends to suggest age or wear |
|---|---|---|
| Shingle creases | Fresh horizontal creases at the nail line; exposed, clean asphalt on the crease | No creasing; brittle shingles that crack when lifted for any reason |
| Missing shingles | Clean tears, shingles found in the yard after the storm, damage concentrated on the windward side | Gaps with weathered edges, shingles missing evenly on every slope |
| Seal strips | Recently broken seals on rows that lie flat in calm weather | Seals that never bonded or failed long ago (dirt and debris in the sealant) |
| Metal panels | Bent panels, bright exposed metal at fastener holes, peeled edges | Long-standing rust streaks, loose fasteners with corrosion |
| Fences | Sections down in the same direction as the storm, freshly snapped posts | Rotted posts at grade, sections leaning gradually over time |
| Timing | Damage first noticed right after a documented storm | No storm on record near the date of loss |
None of these are absolute rules. An older roof can still suffer genuine wind damage, and many policies do not exclude coverage just because a roof is old. What matters is whether a covered peril caused the damage you are claiming. If your claim is denied as wear and tear, read the denial letter closely and see our article on what to do when the insurance company disputes storm damage.
Your claim should name the date of the specific storm that caused the damage. If you pick a date with no wind on record, it gives the insurer an easy reason to question causation. NCEI records and local weather station data can help you pinpoint the right date.
How to document wind damage before cleanup
Insurers expect you to protect the property from further damage, so you may need to tarp a roof or remove a tree from the driveway quickly. Before you do, take a few minutes to capture what happened. Our claim documentation checklist covers the full list; for wind losses, focus on these.
Roof shingles
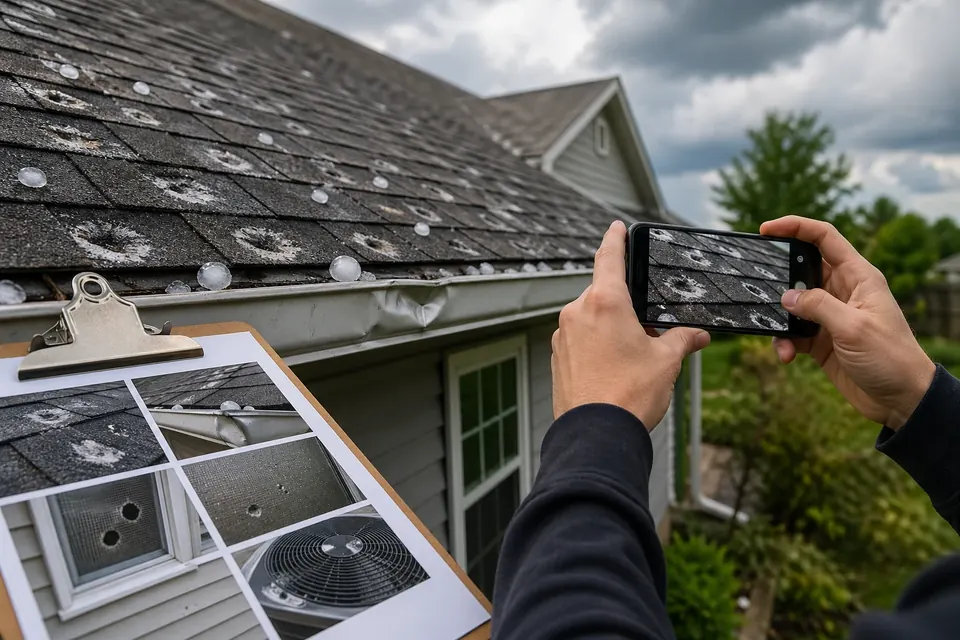
- Take wide photos of each roof slope from the ground, then closer shots of damaged areas if it is safe. Do not climb a damaged roof yourself; a contractor or adjuster can document it.
- Photograph shingles that are lifted, creased, or folded back. A shingle that lies flat may still have a broken seal, so note the location.
- Collect shingles and ridge caps that blew into the yard. Keep a few as physical evidence and photograph where they landed.
- Note the direction each damaged slope faces. Damage concentrated on the side facing the storm supports a wind cause.
Fences, outbuildings, and other structures
- Photograph fence sections from both ends to show the direction they fell, and get close-ups of snapped posts.
- Measure the length of damaged fence and note the material (wood, chain link, wrought iron).
- Document sheds, carports, pergolas, and metal buildings separately. They often fall under "other structures" coverage with its own limit.
Trees and debris
- Photograph the tree where it fell, including what it struck, before removal.
- Show the root ball or the break point. A fresh break in a healthy limb looks different from a long-dead branch.
- Keep invoices for tree removal, tarping, and emergency repairs. Reasonable costs to prevent further damage are often reimbursable.
Interior water
- Photograph ceiling stains, wet drywall, and damaged contents as soon as you see them. Mark the stain edges with pencil and date them if the stains are growing.
- Dry the area promptly. Many policies limit coverage for mold or for damage that gets worse because the owner did not mitigate.
Understanding your wind/hail deductible
Many Texas homeowners policies carry a separate wind and hail deductible, and it is often a percentage of the dwelling (Coverage A) limit rather than a flat dollar amount. That changes the math on whether a claim makes sense.
| Dwelling limit (Coverage A) | 1% wind/hail deductible | 2% wind/hail deductible | 5% wind/hail deductible |
|---|---|---|---|
| $200,000 | $2,000 | $4,000 | $10,000 |
| $300,000 | $3,000 | $6,000 | $15,000 |
| $400,000 | $4,000 | $8,000 | $20,000 |
These are illustrations, not quotes. Your declarations page shows the deductible that actually applies, and some policies also have a separate named-storm or hurricane deductible. If you are unsure whether your damage clears the deductible, our claim calculator can help you estimate it before you decide.
One common mistake: assuming the damage is too small after seeing only one obvious problem, like a few missing shingles. A full inspection sometimes finds damage to ridge caps, flashing, vents, fences, gutters, and screens that adds up. The opposite also happens. If the total is truly below the deductible, a claim may not pay anything, so get an informed estimate first.
Step-by-step: filing a wind damage claim in McAllen
- Stay safe. Watch for downed power lines and do not walk on a damaged roof.
- Document the damage with photos and video before any cleanup or temporary repair.
- Prevent further damage. Tarp openings, board broken windows, and keep receipts.
- Report the claim promptly. Most policies require prompt notice. Write down the claim number and the name of everyone you speak with.
- Identify the storm date. Use NCEI records or the storm lookup tool mentioned above to confirm when the wind event happened at your location.
- Be present at the inspection. Point out every area of damage, including fences, outbuildings, and interior stains. Ask the adjuster what they are seeing and note anything they decline to include.
- Review the estimate line by line. Compare quantities, materials, and whether items like ridge caps, starter, and flashing were included. Our guide on reviewing an underpaid roof insurance estimate walks through the details.
- Respond in writing if you disagree, and include supporting photos, contractor estimates, and weather data.
Texas law sets timelines for how insurers handle claims. Under the Prompt Payment of Claims statute (Texas Insurance Code Chapter 542), an insurer generally has 15 days after notice to acknowledge the claim and begin its investigation, and 15 business days after receiving requested information to accept or reject it, with a possible extension of up to 45 days. Those deadlines may be extended by 15 days after a weather-related catastrophe declared by the Commissioner of Insurance.
When a wind claim is underpaid or denied
Wind claims commonly run into a few recurring problems:
- Spot repairs instead of slope or roof replacement. The estimate pays to replace a handful of shingles even though matching or repairability is a real issue.
- Missing items. Fences, gutters, screens, outbuildings, or interior damage left out of the estimate.
- Causation denials. "Wear and tear," "pre-existing damage," or "improper installation" cited as the reason for denial.
- Combined wind and hail. When one storm causes both, the cause matters less for coverage than making sure all the damage is captured, since both perils are typically handled under the same wind/hail deductible.
If you think the estimate leaves out damage, you can request a re-inspection or submit a supplement with documentation. Our page on insurance claim supplements explains that process. If the insurer accepts that the damage is covered but you disagree on the amount, many policies include an appraisal clause; see insurance appraisal. If the claim was denied outright, our denied insurance claims page covers next steps. For questions about lawsuits, bad faith, or deadlines to sue, talk with a Texas attorney; a public adjuster cannot give legal advice.
How a public adjuster can help with wind damage claims
A licensed Texas public adjuster works for the policyholder, not the insurance company. On a wind claim, that usually means inspecting the full property, documenting damage with photos and measurements, matching the damage to recorded weather events, preparing a detailed estimate (often in Xactimate, the same software many insurers use), and handling communication with the carrier.
Joseph Dittman, a licensed Texas public adjuster, also has background in carrier-side adjusting and appraisal work, which helps when a claim turns on how the insurer is reading the evidence. Learn more on our wind damage claims service page.
Texas regulates public adjusters under Insurance Code Chapter 4102. Fees are disclosed in a written contract before any work begins; Texas law caps public adjuster compensation at 10% of the insurance settlement. You can rescind a public adjuster contract within 72 hours of signing.
Wind damage is not always dramatic. Sometimes it is a few creased shingles that start a slow leak months later. If a storm has passed over your McAllen, Mission, Edinburg, or Pharr property recently, a careful look now can save a harder conversation with your insurer later.
Frequently Asked Questions
Does homeowners insurance cover wind damage in McAllen?
Many standard Texas homeowners policies cover sudden, accidental physical damage caused by windstorm, subject to the deductible, limits, and exclusions in the policy. Because Hidalgo County is not in the TWIA catastrophe area, McAllen homeowners typically get wind coverage from their regular insurer (or the Texas FAIR Plan where applicable). Check your declarations page and policy form to confirm.
How does an insurer decide whether damage is from wind or from wear and tear?
Adjusters typically look at the pattern of damage, the age and condition of the materials, and whether there is evidence of a specific weather event. Fresh creases, recently torn tabs, debris impact, and damage concentrated on the windward side of a structure tend to point toward wind. Granule loss, cracking spread evenly across all slopes, and long-standing rust or rot tend to point toward age. Good photos and weather records can help clarify which story the evidence supports.
What is a wind/hail deductible?
Many Texas policies carry a separate deductible for wind and hail losses, often stated as a percentage of the dwelling (Coverage A) limit rather than a flat dollar amount. For example, a 2% deductible on a $250,000 dwelling limit would be $5,000. Your declarations page lists the deductible that applies.
Is a fallen tree covered by insurance?
It depends on the policy and what the tree hit. Many policies cover damage a wind-blown tree causes to the house or a covered structure, and some include limited coverage for debris removal. Coverage for the tree itself, or for a tree that fell without damaging anything covered, is often limited or excluded. Read the "trees, shrubs and plants" and debris removal sections of your policy.
How long does the insurer have to respond to a wind claim in Texas?
Under the Texas Prompt Payment of Claims statute, an insurer generally has 15 days after notice to acknowledge the claim, begin its investigation, and request information, then 15 business days after receiving requested items to accept or reject (with a possible extension of up to 45 days). These deadlines can be extended by 15 days after a declared weather catastrophe. Surplus lines insurers may have different timeframes.
Can a public adjuster help with a wind claim that was already partially paid?
Yes. A licensed Texas public adjuster can review the insurer's estimate, document damage that may have been missed, and prepare a supplement or reopen discussions on your behalf. Results depend on the policy and the facts, and fees are disclosed in a written contract before any work begins.
Sources and further reading
This article is general information about property insurance claims in Texas, not legal advice, and not a promise of any coverage or outcome. Your policy language and the facts of your loss control your claim.